
IRS Hardship Program
Stop IRS Collections & Get Financial Relief Fast
$0M+


Discover how much tax debt forgiveness you qualify for.
If you’re struggling to keep up with IRS debt and basic living expenses, the IRS Hardship Program may give you the relief you need. When approved, it can pause IRS collections immediately, protecting you from levies, garnishments, and aggressive enforcement. But here’s what most people don’t realize:
It’s not automatic, It’s not permanent, And how you apply can determine whether you get approved or denied. That’s where strategy, and the right legal guidance, makes all the difference.
Hardship collection relief and a tax-refund request are different issues. A financial hardship does not automatically create a refund or release an offset. The correct next step depends on whether the refund is delayed, applied to another debt, offset through the Treasury Offset Program, or affected by a separate IRS processing issue. Review the notice and the specific refund or offset facts before choosing a form or requesting relief.

What Is the IRS Hardship Program?
The IRS Hardship Program, also known as Currently Not Collectible (CNC) status, is a form of relief that temporarily stops the IRS from collecting your tax debt. In simple terms, it tells the IRS:
“Right now, I genuinely cannot afford to pay without sacrificing basic living needs.”
If approved, the IRS will pause most collection actions. This means no bank levies, no wage garnishments, and no aggressive enforcement, giving you time to stabilize financially.
However, it’s important to understand that this does not erase your tax debt. The balance may continue to grow due to interest, and your financial situation will be reviewed periodically.
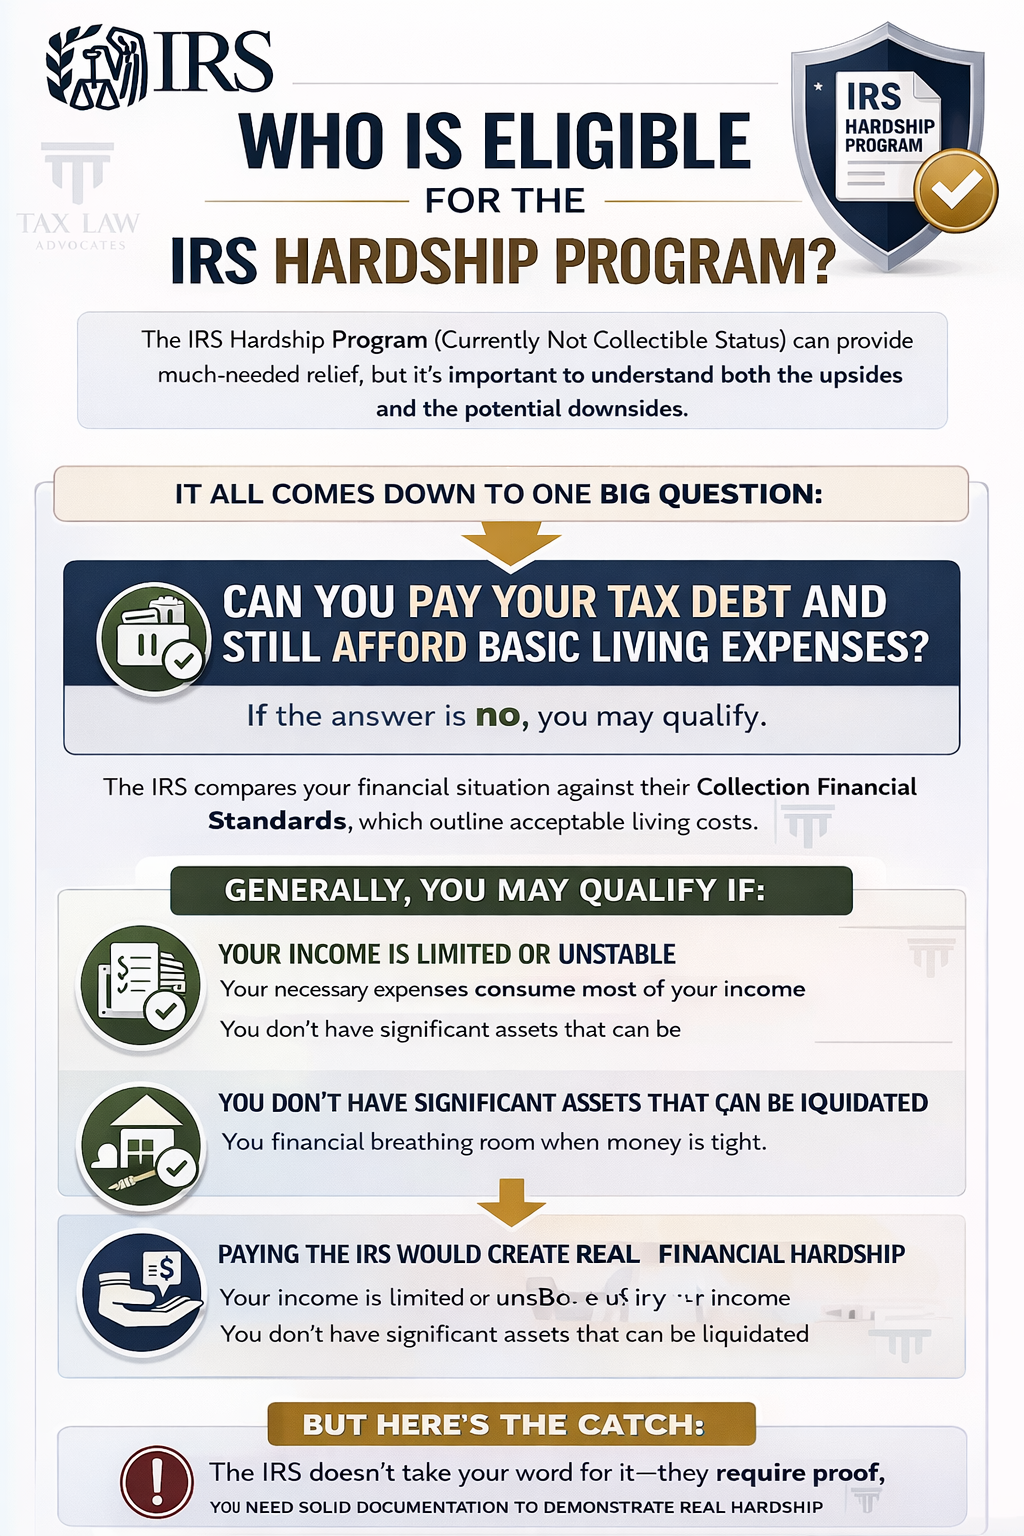
IRS hardship program eligibility
Eligibility for the IRS hardship program, or Currently Not Collectible status, is determined by comparing a taxpayer’s allowable expenses under IRS Collection Financial Standards against verified gross income, with no discretionary income remaining for tax payment. The IRS also reviews asset equity, as significant realizable assets can disqualify an otherwise income, eligible taxpayer. Tax Law Advocates assesses both income and asset criteria to determine genuine eligibility before filing.
Eligibility comes down to one core question:
Can you pay your tax debt and still afford basic living expenses?
If the answer is no, you may qualify. The IRS compares your financial situation against their Collection Financial Standards, which outline acceptable living costs.
What does financial hardship mean to the IRS?
Financial hardship generally means that paying the IRS would prevent you from meeting necessary living expenses. The IRS may review verified income, allowable expenses, asset equity, filing compliance, and collection potential. A hardship claim is supported by financial documentation; a general statement that the balance is difficult to pay is not enough by itself.
But here’s the catch:
The IRS doesn’t take your word for it, they require proof. That’s where many applications fail.
How to apply for IRS hardship relief
Applying might seem straightforward, but this is where most people make costly mistakes. The process involves gathering financial documentation, completing disclosure forms, and submitting everything in a way that clearly demonstrates hardship.
1. Review the IRS notice and identify the collection action.
2. Confirm that required tax returns are filed.
3. Gather income, expense, asset, and liability records.
4. Complete the financial information requested for your situation.
5. Submit supporting documentation and respond to IRS follow-up requests.
6. Continue meeting filing and payment obligations while the request is reviewed.
What information is needed for an IRS hardship review?
Depending on the collection issue, the IRS may request information about wages, self-employment income, benefits, housing, transportation, healthcare, bank accounts, investments, vehicles, real estate, dependents, and other assets. The correct financial statement or supporting form depends on the taxpayer’s circumstances and the IRS request. Do not assume that one hardship form applies to every case.
What is Form 911?
Form 911 is used to request help from the Taxpayer Advocate Service (TAS) an independent organization within the IRS. It’s typically used when you’re facing urgent financial hardship or when normal IRS processes aren’t resolving your issue. Think of it as an escalation tool when your situation needs immediate attention.
When Should I Use Form 911?
You should consider using Form 911 if your situation is urgent or not being handled properly through normal channels.
If you are experiencing financial difficulties
When your situation is affecting your ability to meet basic needs.
If you are facing an immediate threat
Such as a levy, garnishment, or asset seizure.
If you have not received a response from the IRS
Delays can make things worse, especially when penalties continue to grow.
When should I not use this form?
If your case is progressing normally or doesn’t involve urgent hardship, it may not be necessary.
What should I expect to happen next?
Once submitted, a Taxpayer Advocate reviews your case and works directly with the IRS to resolve the issue faster.
IRS hardship refund request
A hardship-based refund release differs from a routine refund delay in that it requires the taxpayer to affirmatively demonstrate immediate economic harm, not merely inconvenience from IRS processing time. The Taxpayer Advocate Service prioritizes cases involving imminent negative consequences, such as inability to pay for housing, utilities, or medical care. Tax Law Advocates evaluates whether a taxpayer’s circumstances meet this threshold before submitting a hardship refund request, and can advise whether a related installment agreement or Currently Not Collectible status is also needed for the broader liability.
IRS hardship refund request form
Taxpayers experiencing an immediate financial hardship, such as eviction or inability to pay for necessities, can request expedited release of a refund by filing Form 911, Application for Taxpayer Assistance Order, with the Taxpayer Advocate Service. The form requires documented proof of hardship, since the IRS does not expedite refunds based on financial need alone. Tax Law Advocates assists taxpayers in preparing Form 911 with the substantiation the Taxpayer Advocate Service requires for approval, as part of our broader IRS Hardship Program representation.
IRS hardship application
Application for IRS hardship status, formally known as Currently Not Collectible designation, requires submission of Form 433-A or 433-F documenting income, necessary living expenses, and assets, which the IRS evaluates against Collection Financial Standards. Approval temporarily suspends active collection, including levies and wage garnishment, without eliminating the underlying liability or stopping penalty and interest accrual. Tax Law Advocates prepares hardship applications with attorney-verified financial documentation to withstand IRS scrutiny.
How do I qualify for an IRS hardship?
Qualification for IRS hardship status requires demonstrating that necessary living expenses, as defined under IRS Collection Financial Standards, equal or exceed the taxpayer’s monthly income, leaving no funds available for tax payment. The IRS independently verifies reported expenses against national and local standards rather than accepting self-reported figures at face value. Tax Law Advocates conducts a pre-filing financial analysis to confirm hardship qualification before submission, and can compare this option against an Offer in Compromise if a permanent resolution fits better.
Explore IRS financial hardship program
The IRS financial hardship program suspends collection enforcement, such as levies and wage garnishment, when a taxpayer’s documented necessary expenses leave no ability to pay toward a tax liability. This status is reassessed periodically, and the IRS may resume collection if the taxpayer’s financial circumstances improve or if a new tax year’s liability accrues. Tax Law Advocates guides taxpayers through both initial qualification and the ongoing compliance required to maintain hardship status, following our process for long-term resolution.
How do I file a hardship with the IRS
Filing for IRS hardship status involves submitting a completed Collection Information Statement, either Form 433-A or 433-F, directly to the IRS Collection function or Automated Collection Service, along with supporting financial documentation. The filing can be initiated independently or through an authorized representative under a Power of Attorney (Form 2848). Tax Law Advocates files hardship requests on the taxpayer’s behalf under Power of Attorney, managing all subsequent IRS correspondence.
How to write a hardship letter to the IRS
An effective hardship letter to the IRS states the specific financial hardship clearly, references supporting documentation such as pay stubs or medical bills, and aligns the taxpayer’s reported expenses with IRS Collection Financial Standards categories. Vague assertions of hardship without corresponding financial evidence are routinely insufficient for IRS approval. Tax Law Advocates drafts hardship letters that integrate directly with the taxpayer’s supporting financial documentation for consistency, contact us to have your case reviewed before you file.
IRS hardship letter template
While IRS hardship letter templates provide a structural starting point, the IRS evaluates hardship claims based on specific, documented financial facts rather than the letter’s format or tone. Effective correspondence pairs the narrative with supporting financial statements and Collection Financial Standards calculations. Tax Law Advocates prepares hardship correspondence as part of a complete, documentation-backed submission rather than a standalone letter.
What does the IRS consider a financial hardship?
The IRS defines financial hardship as a taxpayer’s inability to pay reasonable basic living expenses, measured against Collection Financial Standards covering housing, utilities, transportation, food, and healthcare, rather than a subjective assessment of need. Expenses exceeding IRS local and national standards are generally not counted toward the hardship determination unless specifically substantiated. Tax Law Advocates calculates allowable expenses under current IRS standards to accurately assess hardship qualification.
IRS hardship form for individuals
Individual taxpayers apply for hardship status using Form 433-F, Collection Information Statement, or the more detailed Form 433-A, depending on the complexity of the case and the IRS employee handling it. These forms require full disclosure of income sources, monthly expenses, bank accounts, and asset holdings, subject to IRS verification. Tax Law Advocates ensures individual hardship forms are completed accurately to avoid processing delays or requests for additional information.
Why Work with a Tax Attornry for IRS Hardship Program
This is where your outcome can change significantly. The IRS Hardship Program isn’t just about filling out forms, it’s about proving your case in a way the IRS accepts. A tax attorney brings:
- Legal authority in dealing with the IRS
- Deep understanding of IRS evaluation standards
- Ability to structure financial disclosures strategically
- Experience in handling denials and escalations
Most importantly: You’re not guessing, you’re building a case that works.
Why Tax Law Advocates
At Tax Law Advocates, we focus on outcomes—not volume.We combine legal expertise with real-world IRS negotiation experience to give clients the strongest chance of approval.
✔ 16+ years of experience
✔ Attorney-led representation
✔ Nationwide service
✔ Proven IRS negotiation success
✔ Transparent, ethical approach
✔ Bilingual support available
You’re not just another case—you’re a strategy.
Tax Attorney: David Cho
Tax Attorney David Cho leads tax resolution strategy at Tax Law Advocates with advanced expertise in IRS hardship programs and tax debt resolution. He earned both his J.D. and LL.M. in Taxation from the University of California, Irvine School of Law and works directly with the IRS to help clients facing wage garnishments, bank levies, and serious financial hardship.
Known for his practical, results-driven approach, David has helped clients pursue relief through programs such as Currently Not Collectible (CNC) status and Offer in Compromise settlements, helping individuals regain financial stability and move forward with confidence.
Real Client
Scenarios
One client came to us facing wage garnishment while struggling to pay rent. After reviewing their financials, we successfully positioned their case for hardship status, stopping collections immediately.Another client assumed they had no options. By restructuring their financial presentation, we demonstrated hardship and prevented enforcement actions.
In a third case, we combined hardship status with a long-term resolution strategy, giving the client both immediate relief and a path forward.
Meet Your Lead Tax Attorney and Enrolled Agent for IRS Debt Relief & Tax Resolution You Can Trust
David Cho
David Cho
Scott Mullerleile
EA with 12+ years in tax resolution and a background in collections. Scott has successfully handled hundreds of cases, including accepted Offers in Compromise and representation before Revenue Officers, audits, and appeals.
Our IRS Tax Relief Results by the Numbers
Proven results helping clients resolve IRS and state tax debt nationwide.
$0M+
Tax Debt Resolved for Clients
0K+
Clients served
0%
Handled by Tax Attorneys
0%
Cases Successfully Resolved
24hr
Average Case Action Time
0
Years of experience
Tax Law Advocates Client Success Stories
Jonnel Bolotano with Tax Law Advocates was amazing to work with. Even though I didn’t initially start my case with him, he stepped in, took charge, and stayed on top of everything from that point forward.

ItzMiBaebii
If I could give Tax Law Advocates more than 5 stars, I absolutely would. Jamie and Scott were my dream team, steady, sharp, and on top of every detail. I came in with a heavy tax burden that felt like it would follow me forever...

Rebecca Ingram
Jesse Moreno my tax lawyer did a wonderful job on my case. She was very patient kind and professional, and resolution that I received was better than I expected! Thank you Jesse for representing me!

Debbie Kern
FAQ
What is the IRS hardship program?
It’s a program that pauses IRS collections when you cannot afford to pay.
Does hardship status forgive my tax debt?
No, it pauses collections but does not eliminate the debt.
How long does CNC status last?
It can last months or years, depending on your financial situation.
Will the IRS check my finances again?
Yes, they review your situation periodically.
Can I apply on my own?
Yes, but improper applications are often denied.
What forms are required?
Typically Form 433-F or 433-A.
Will interest stop?
No, interest may continue to accrue.
Can I still get levied?
Not while in active CNC status.
What happens if I get denied?
You may need to pursue another resolution option.
Do I need a tax attorney?
Not required—but highly recommended.